
UAE commercial vehicle insurance follows a strict rulebook. In fact, the Central Bank sets a minimum and a maximum premium for every class of pickup, truck, tanker, bus and machine. So your insurer cannot simply charge what it likes. However, most transport operators never see those official numbers. Therefore, we publish them here in full, straight from the regulation.
Also, we explain the fleet discount and the deductible caps. Then we list five mistakes that let an insurer refuse a truck claim. GS Insurance Services places this business every day across all seven emirates. So we know where operators lose money. For private cars, see our main UAE car insurance guide instead.
What UAE commercial vehicle insurance must cover
The UAE runs two standard motor policies. Both apply to commercial vehicles.
- Third Party Liability (TPL). This is the legal minimum. It pays other people for injury and damage. However, it pays nothing for your own truck.
- Loss and Damage plus TPL. Operators call this comprehensive. It also repairs or replaces your own vehicle.
Both policies run for 13 months, not 12. Furthermore, every policy names a purpose of use. The official application form lists private, commercial, rental and driving education. Therefore, a truck that works for hire needs commercial use written on the policy. Otherwise the insurer can reject the claim later.
Insurance also comes before the plate. The UAE Government portal lists it as a registration step: you must get vehicle insurance from an authorised insurer before you register.
UAE commercial vehicle insurance rates for pickups and trucks
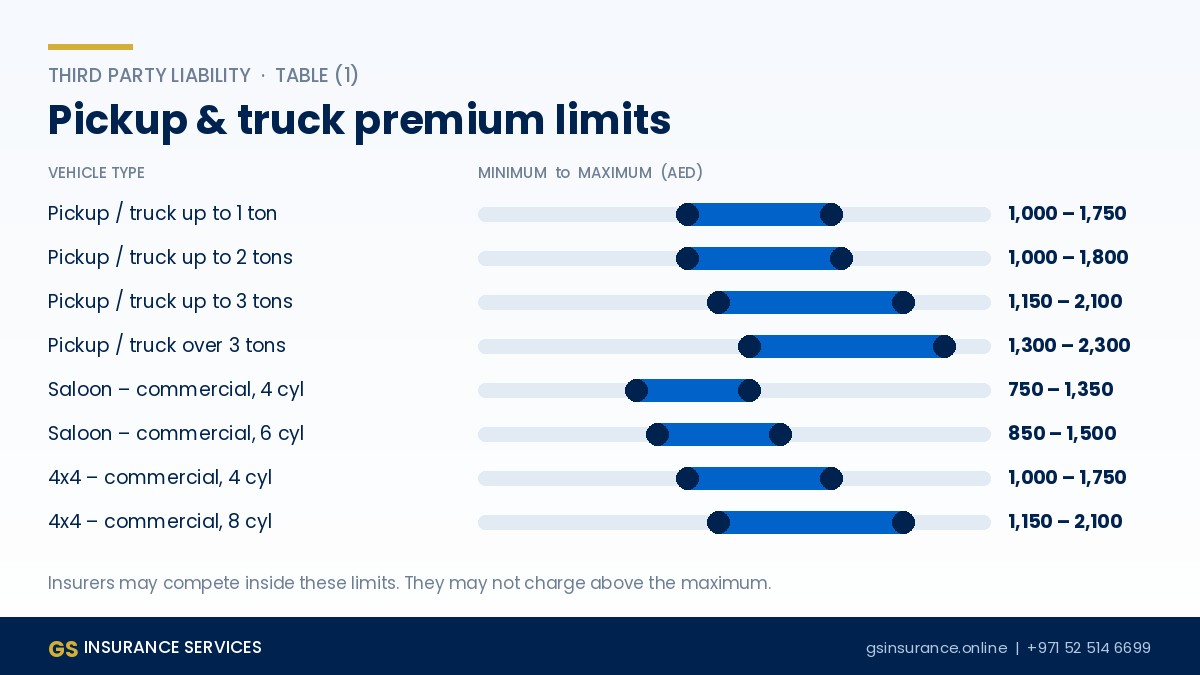
Table (1) of the tariff regulation caps third party premiums. These are the official figures for a 13-month period.
| Vehicle type | Minimum (AED) | Maximum (AED) |
|---|---|---|
| Pickup & truck up to 1 ton | 1,000 | 1,750 |
| Pickup & truck up to 2 tons | 1,000 | 1,800 |
| Pickup & truck up to 3 tons | 1,150 | 2,100 |
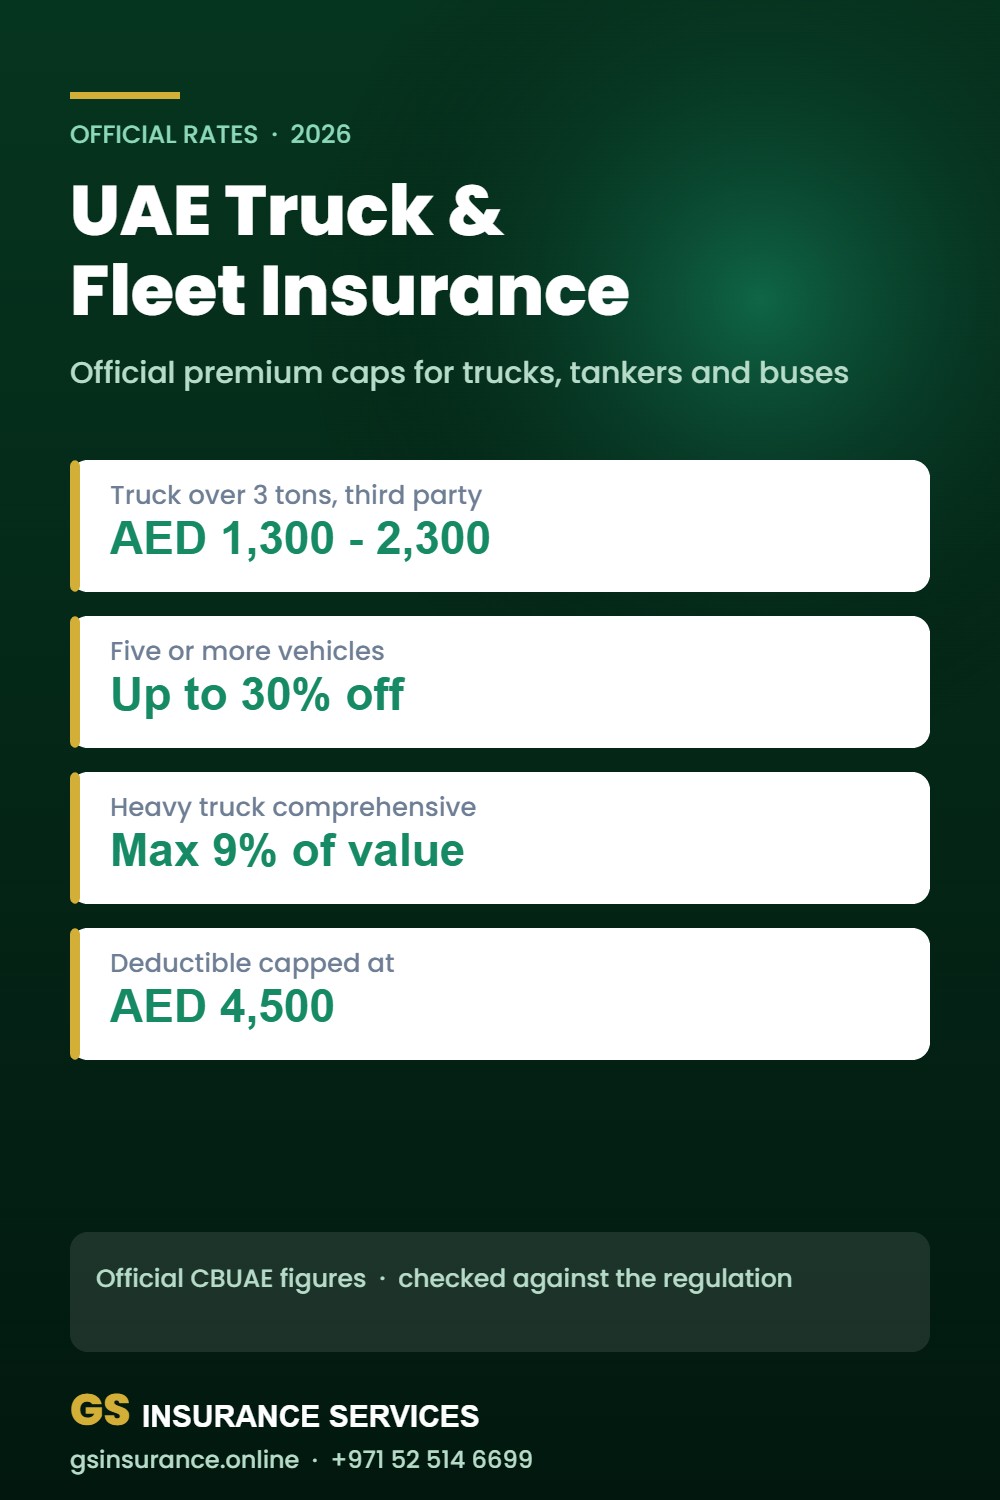
| Pickup & truck more than 3 tons | 1,300 | 2,300 |
| Saloon – commercial, 4 cylinders | 750 | 1,350 |
| Saloon – commercial, 6 cylinders | 850 | 1,500 |
| Four-wheel drive – commercial, 4 cylinders | 1,000 | 1,750 |
| Four-wheel drive – commercial, 8 cylinders | 1,150 | 2,100 |
So a three-tonne pickup cannot cost more than AED 2,100 for third party cover. If a quote comes back higher, then ask for the breakdown. Insurers may compete inside these limits, but they may not go above them.
Tankers, trailers, buses and heavy equipment
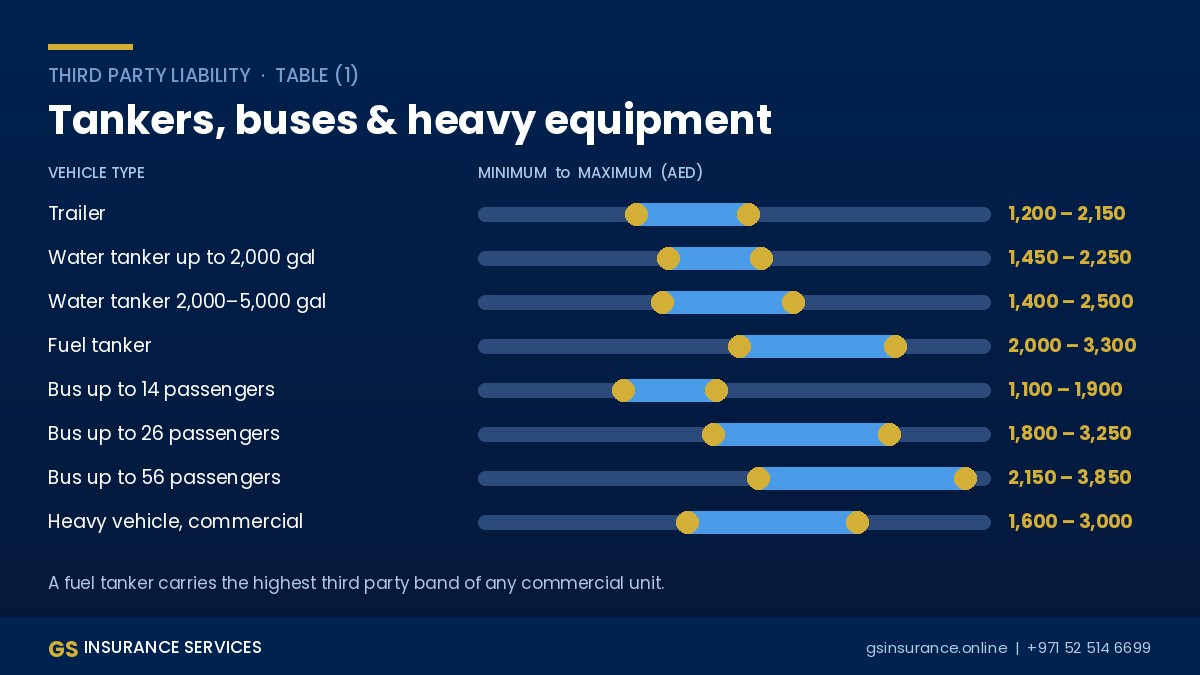
Heavier units carry their own bands. Because the risk rises, the caps rise too.
| Vehicle type | Minimum (AED) | Maximum (AED) |
|---|---|---|
| Trailer | 1,200 | 2,150 |
| Water tanker up to 2,000 gallons | 1,450 | 2,250 |
| Water tanker 2,000 to 5,000 gallons | 1,400 | 2,500 |
| Water tanker trailer | 1,500 | 2,500 |
| Fuel tanker | 2,000 | 3,300 |
| Bus up to 14 passengers | 1,100 | 1,900 |
| Bus up to 26 passengers | 1,800 | 3,250 |
| Bus up to 56 passengers | 2,150 | 3,850 |
| Light equipment, dumper & agriculture | 1,000 | 2,500 |
| Forklift & light equipment, commercial | 1,300 | 2,500 |
| Heavy vehicle, commercial | 1,600 | 3,000 |
Notice the fuel tanker band. It sits far above a plain trailer, because the cargo carries far more risk.
Comprehensive cover: minimum premium and maximum rate
Table (2) works differently. It sets a minimum premium in dirhams and a maximum rate as a percentage of the vehicle value.
| Vehicle type | Minimum premium (AED) | Maximum rate |
|---|---|---|
| Pickup and van up to 3 tons (light) | 1,550 | 7% |
| Heavy truck, more than 3 tons | 2,000 | 9% |
| Bus up to 15 seats, commercial | 1,950 | 7% |
| Bus up to 26 seats, commercial | 2,400 | 7% |
| Bus up to 56 seats, commercial | 2,500 | 7% |
| Equipment | 2,750 | 7% |
Therefore a heavy truck worth AED 200,000 cannot carry a comprehensive premium above AED 18,000. Meanwhile the floor stays at AED 2,000.
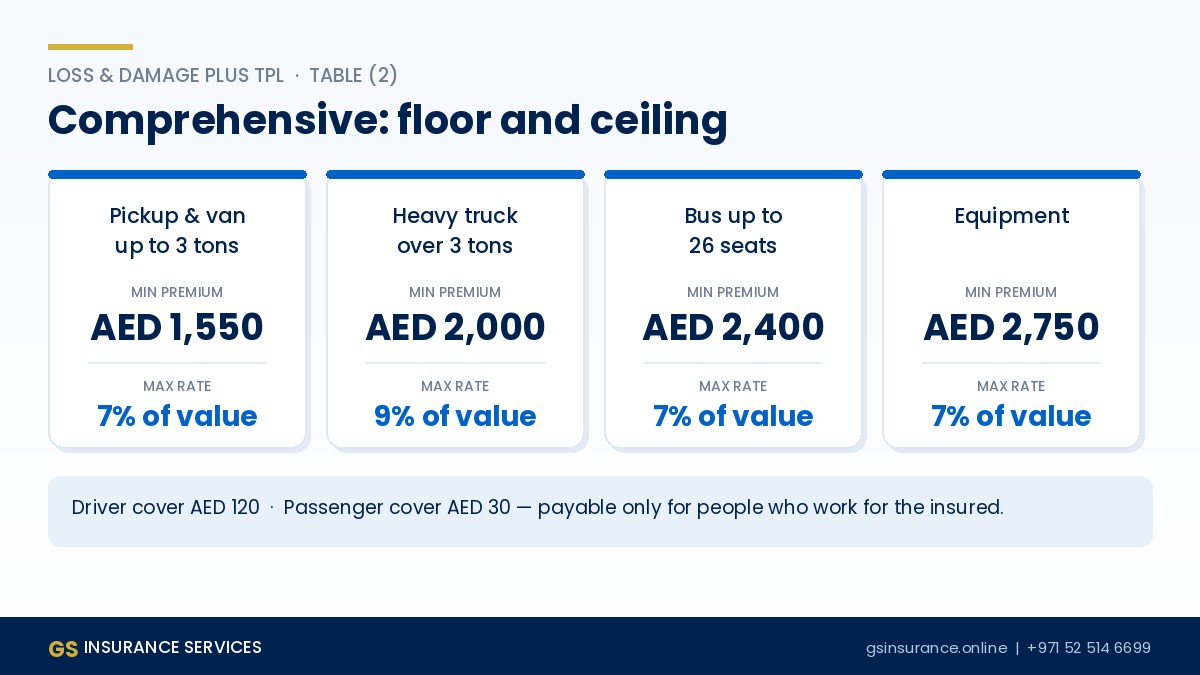
Two small add-ons also sit in the regulation. Driver cover costs AED 120. Passenger cover costs AED 30. Still, the passenger premium applies only to people who work for the insured. So a transport company covering its own crew pays it, while a general haulier may not need it.
UAE commercial vehicle insurance for fleets of five or more
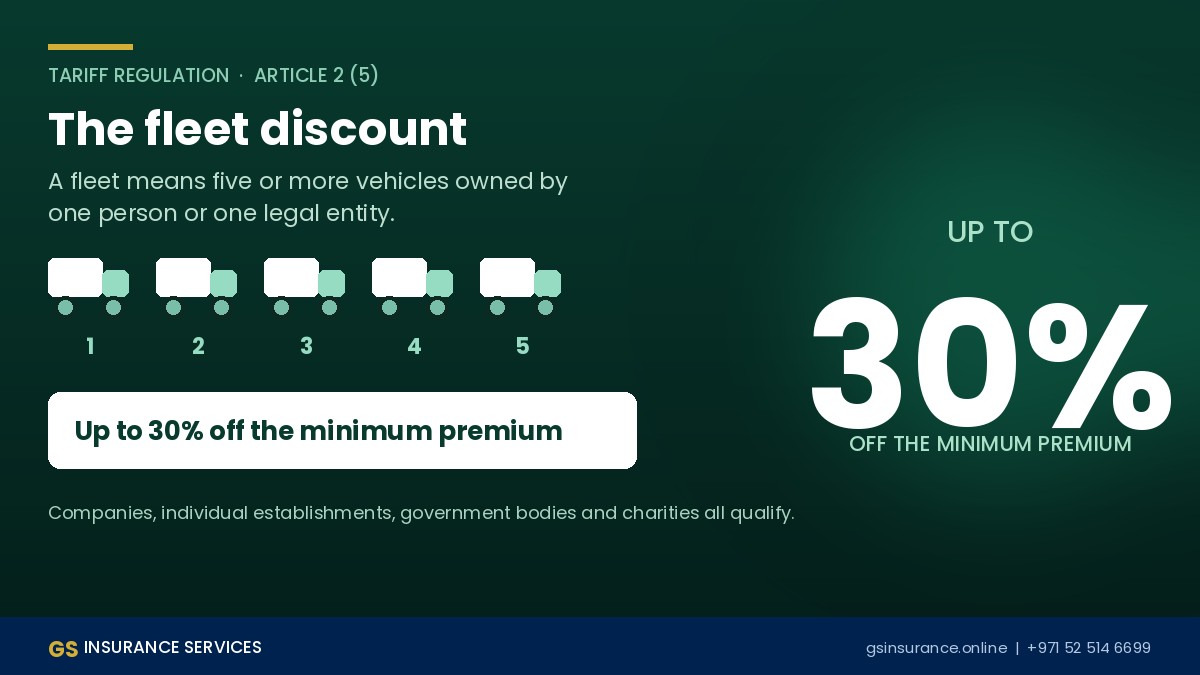
Here is the rule most operators miss. The regulation defines a fleet as five or more vehicles owned by one person or one legal entity. That includes companies, individual establishments, government bodies and charities.
Once you qualify, the insurer may cut up to 30% off the minimum premium. In short, five trucks under one trade licence unlock a discount that five separate owners never get.
The regulation protects fleet policies in another way too. An insurer may not sign any side agreement that reduces the cover on a fleet policy, or that blocks a claim for a reason unrelated to the accident. Any such agreement counts as void.
So if you run pickups, trucks and staff buses together, then insure them under one fleet policy. Generally you gain on price, on paperwork and on renewal dates.
UAE commercial vehicle insurance discounts for individual owners
Single-vehicle owners get a different set of reductions. The regulation lists them clearly:
- 10% off the minimum premium after one claim-free year.
- 15% after two claim-free years.
- 20% after three claim-free years.
- 10% loyalty discount when you renew with the same insurer.
- 25% at renewal for vehicles running on gas or electricity.
- 50% for medical workers, armed forces, police, civil defence, people of determination, and people above 60.
However, these do not stack. When more than one reason applies, only the highest single reduction counts. Also, your insurer must give you a free claims-experience certificate on request. So always ask for it before you move insurer.
What you pay out of pocket after an accident
The Basic Deductible sits in Schedule (3) of the policy. Commercial units carry the heaviest caps.
| Vehicle | Maximum deductible per accident |
|---|---|
| Private vehicles over 12 passengers, rental vehicles, trucks over 3 tons | AED 1,700 |
| Trucks over 3 tons, passenger buses, industrial vehicles for construction and agricultural work | AED 4,500 |
On top of that, the insurer may add a percentage deductible. For taxi and public transport vehicles the maximum is 10%. For rental vehicles it reaches 20%. Meanwhile a driver under 25 adds up to 10%.
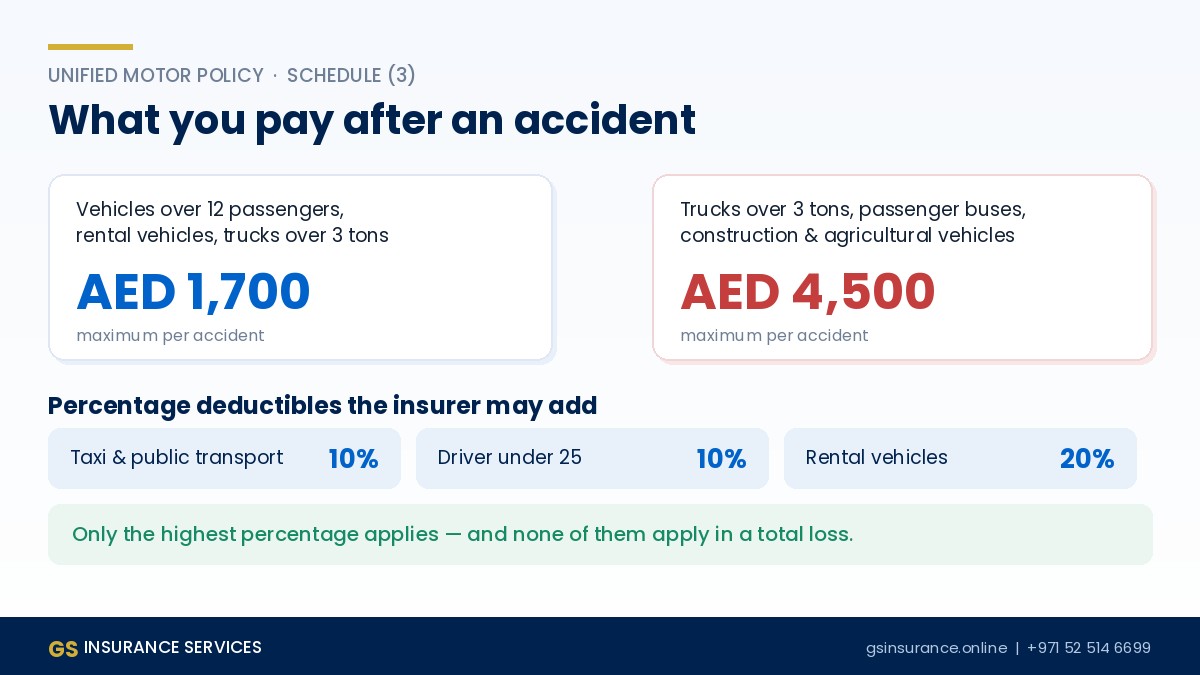
Two protections matter here. First, only the highest percentage applies when several could apply. Second, the percentage deductibles do not apply at all in a total loss. Furthermore, the insurer charges the deductible to the party who caused the accident. So a not-at-fault operator should not carry it. We break the whole system down in our guide to car insurance excess in the UAE.
Depreciation hits commercial vehicles harder
When you ask for brand-new parts, you pay a depreciation share. Private vehicles follow Schedule (1). Taxis, public transport and rental vehicles follow the steeper Schedule (2).
| Year of use | Private vehicle | Taxi, public transport, rental |
|---|---|---|
| First | Nil | 10% (last six months) |
| Second | 5% | 20% |
| Third | 10% | 25% |
| Fourth | 15% | 30% |
| Fifth | 20% | 35% |
| Sixth and above | 30% | 40% |
So a four-year-old rental van pays 30% of a new-parts invoice, while a private car of the same age pays 15%. Therefore many operators simply accept quality used parts instead.
Five mistakes that let an insurer refuse a truck claim
These come straight from the exclusions and recourse chapters. In short, they cost operators real money every month.
- Wrong purpose of use. The policy excludes use for purposes other than those in the insurance application. So never run a commercial job on a private policy.
- Overloading. The policy excludes damage from overload, or from exceeding permitted width, length or height, or from carrying more passengers than licensed. Moreover, the insurer can recover money already paid.
- An undeclared trailer. If a trailer or semi-trailer causes an accident and you never told the insurer about it, then the insurer can claim the compensation back from you.
- Unsecured load. Recourse also applies when the loading was not secured correctly and that caused the accident.
- Wrong licence category. Cover falls away when the driver holds no licence for that class of vehicle. So check every driver’s licence class before the truck moves.
Also remember off-road damage. The standard policy excludes it unless you buy a rider. Therefore quarry, desert and site work needs that extension in writing. Site machinery usually sits under a separate contractors plant and machinery policy instead.
One more gap catches hauliers. Motor cover protects the vehicle, not the load. So goods in transit need cargo insurance on top. Meanwhile your drivers need workmen compensation cover under UAE labour rules.
How to arrange UAE commercial vehicle insurance
Buying UAE commercial vehicle insurance stays simple. First, list every vehicle with its tonnage, seats and value. Second, decide TPL or comprehensive for each unit. Third, count your vehicles, because five or more unlocks the fleet discount. Finally, compare quotes against the official caps above.
GS Insurance Services arranges commercial motor cover for transport pickups, trucks, trailers, tankers, heavy vehicles and equipment. We also handle staff buses and private saloon and station vehicles. So you can keep the whole fleet on one renewal date.
Send your fleet list on WhatsApp: +971 52 514 6699 and we will come back with rates. Alternatively, use our contact page or read our car insurance service page.
Running five or more vehicles under one owner? Our dedicated guide to motor fleet insurance in the UAE covers the 30% reduction, the official fleet definition and the cover an insurer cannot legally cut.
Frequently asked questions
How many vehicles make a fleet in the UAE?
Five. The regulation counts five or more vehicles owned by one person or one legal entity. Therefore a company with five pickups qualifies.
How much is the UAE commercial vehicle insurance fleet discount?
Up to 30% of the minimum premium. However, the insurer decides the exact figure based on your claims record.
Can I insure a commercial truck on a private policy?
No. The policy excludes use for purposes other than those stated in the application. So the insurer can refuse the claim and recover any payment already made.
What is the maximum excess on a heavy truck?
Schedule (3) sets AED 4,500 for trucks over 3 tons, passenger buses and industrial vehicles used in construction and agricultural work.
Does the percentage deductible apply in a total loss?
No. The policy states clearly that percentage deductibles do not apply when the vehicle is a total loss.
How long does a commercial motor policy run?
Thirteen months. The regulation fixes the insurance period at 13 months for every motor policy.
Do I need to declare my trailer?
Yes. If an undeclared trailer causes an accident, then the insurer can recover the compensation from you.
Related guides: car insurance claim UAE
Sources
- CBUAE Rulebook – Motor Vehicle Insurance Tariffs, Decision No. 30 of 2016
- CBUAE Rulebook – Unified Motor Vehicle Insurance Policy Against Loss and Damage
- The Official Portal of the UAE Government – Registering vehicles
GS Insurance Services works as a sales intermediary. A licensed UAE insurance company issues and underwrites every policy. This article gives general information based on the published regulation, and it is not advice on any specific policy. Always read your own policy schedule and confirm the terms with your insurer.