Third party car insurance is the cover every UAE driver must hold. Still, most drivers buy it knowing only the price. Meanwhile they never see what it pays, what it refuses, or when the insurer can come back and take the money from them.
So here is the whole picture, straight from the Unified Motor Vehicle Insurance Policy Against Third Party Liability. Also, we set out the legal price bands, the payout limits, and the daily payment that almost nobody claims.
What third party car insurance covers in the UAE
The name gives away the limit. In short, your policy pays the other person, not you.
Two things are covered when your vehicle causes an accident:
- Bodily injury to a third party, whether they were inside or outside the vehicle.
- Property damage belonging to a third party.
Your own car falls outside it. So do your own injuries. Instead you need full cover, which we explain in our UAE private car insurance guide.
However, the phrase “third party” is wider than most people think. First, it takes in your passengers. Second, it takes in your spouse, parents and children. Third, it takes in the driver of a rental car, a public bus or a driving-school car.
What UAE third party car insurance costs
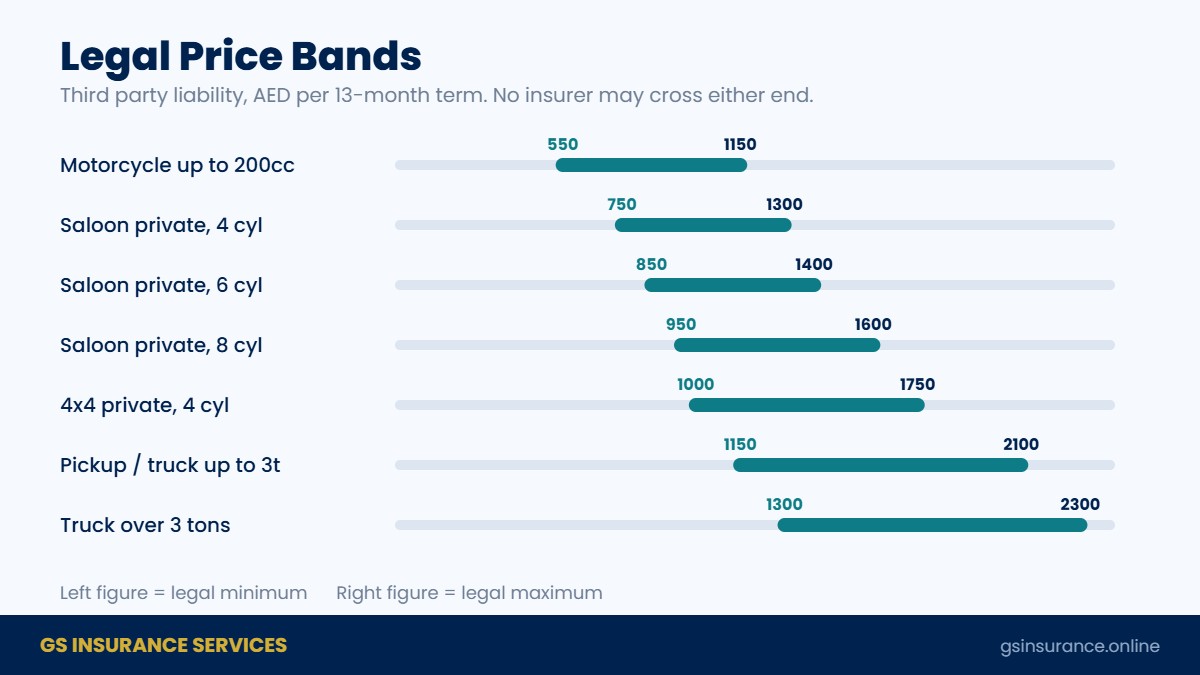
The tariff rules fix a floor and a ceiling for every vehicle class. So no insurer may go under the low figure, and none may pass the high one. Also, each price covers a full term, which runs for 13 months rather than 12.
| Vehicle | Minimum | Maximum |
|---|---|---|
| Saloon private, 4 cylinders | AED 750 | AED 1,300 |
| Saloon private, 6 cylinders | AED 850 | AED 1,400 |
| Saloon private, 8 cylinders | AED 950 | AED 1,600 |
| Four-wheel drive, 4 cylinders | AED 1,000 | AED 1,750 |
| Four-wheel drive, 6 cylinders | AED 1,050 | AED 1,900 |
| Pickup or truck up to 3 tons | AED 1,150 | AED 2,100 |
| Truck over 3 tons | AED 1,300 | AED 2,300 |
| Bus up to 14 passengers | AED 1,100 | AED 1,900 |
| Motorcycle up to 200cc | AED 550 | AED 1,150 |
Use the table as a test. Therefore a quote far under the floor is not a bargain, because no licensed insurer may write it. Meanwhile our guide to insurance scams in the UAE covers the other warning signs.
Discounts are real, though. First, claim-free years give you 10%, 15% or 20%. Second, renewing with the same insurer gives 10%. Third, a gas or electric car gives up to 25%. Finally, 50% goes to medical staff, armed forces, police, civil defence, people of determination and anyone over 60. Yet only the highest single cut applies.

The payout limits behind third party car insurance
Here is where the policy turns surprising. In fact, the limits are not what most drivers assume.
| What happened | What the insurer pays |
|---|---|
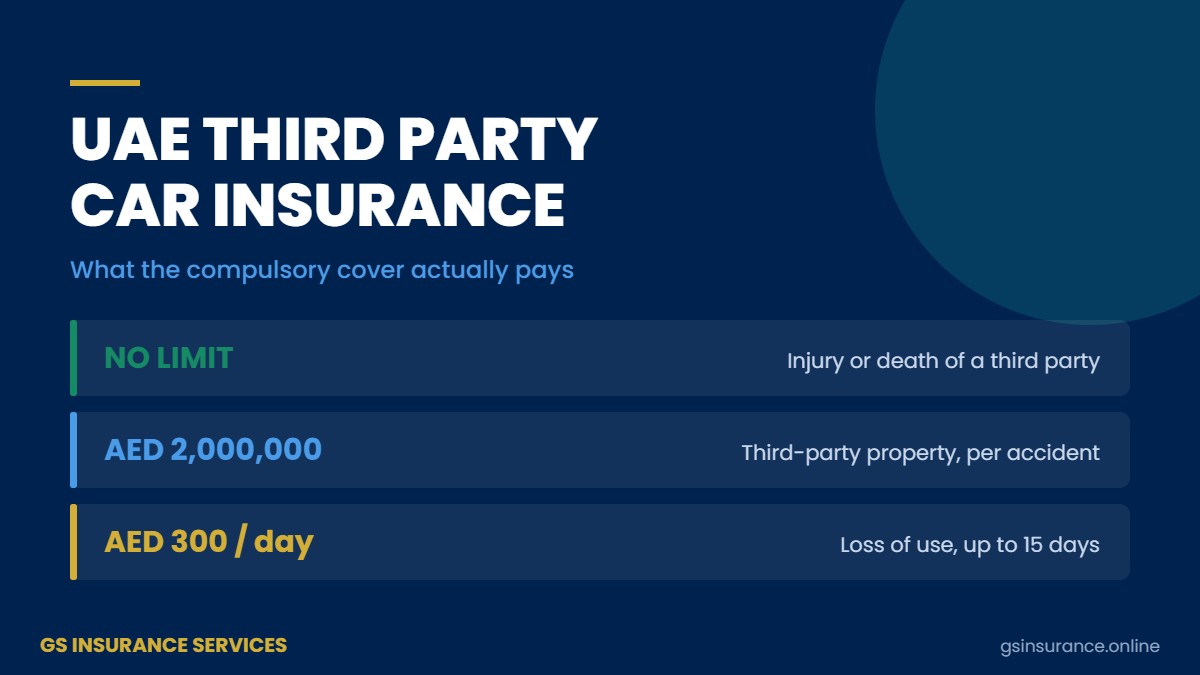
| Injury or death of a third party | Whatever the court awards, with no ceiling |
| Death of your spouse, parent or child | AED 200,000 per person |
| Damage to third-party property | AED 2,000,000 per accident |
| Ambulance and transport to hospital | AED 6,770 per injured person |
Read the first row again. Injury and death carry no limit at all. Whatever a UAE court awards, your insurer pays. Also, that includes the other side’s legal costs, though never fines.
Meanwhile the AED 2 million limit for property runs per accident, however many owners lost something. Furthermore, it takes in the cost of towing the damaged car to a repair shop.
One more rule guards the injured party. Simply put, the insurer may not take any excess out of a third party’s payment. So the excess you see on your own claim never reaches them. Instead, our guide to car insurance excess shows where that excess does bite.
The AED 300 a day almost nobody claims
This right sits in the policy, yet few drivers ever ask for it.
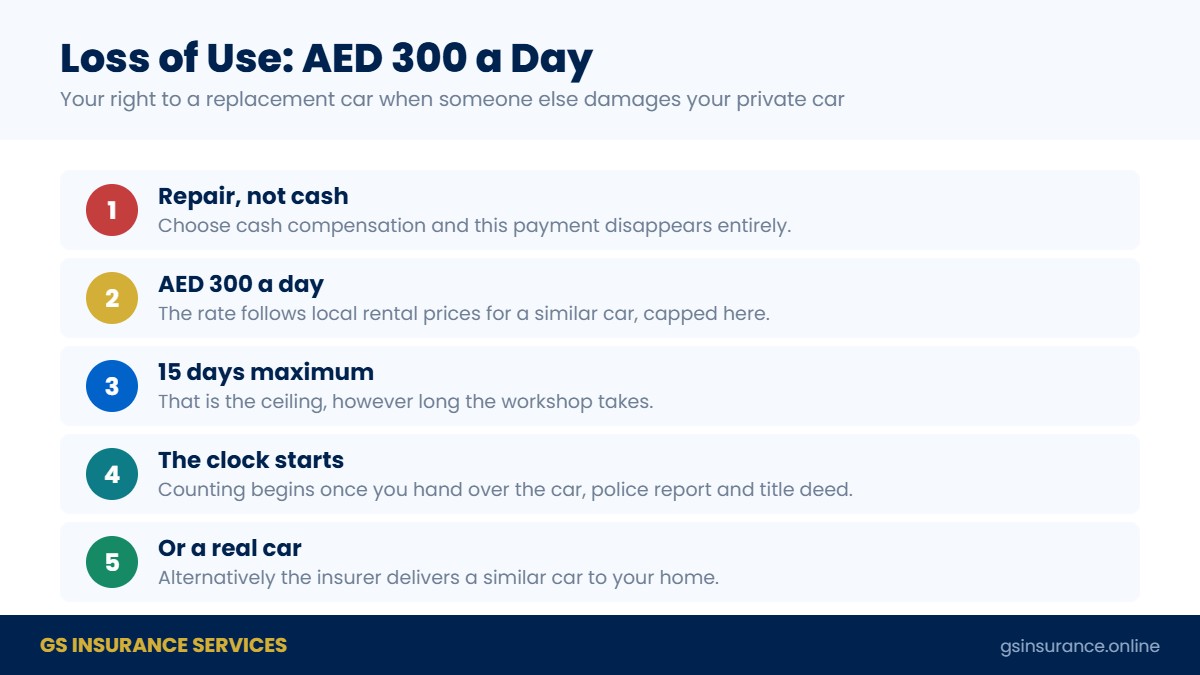
Where someone else hits your private car, you may claim a loss of use payment while the shop works on it. In plain terms, that means a spare car or the cash instead.
- The day rate follows the local rental price for a similar car, capped at AED 300 a day.
- The maximum period is 15 days.
- Counting starts once you hand over the car, the police report and the title deed.
- Take cash instead of a repair, and the payment vanishes.
- Alternatively the insurer may just deliver a similar car to your home.
Notice the fourth point. Take the money and walk away, and you lose this. Also, where you hold full cover too, you may claim from your own insurer, who then bills the other side.
How repairs work under third party car insurance
Here, the age of the damaged car decides everything.
In the first year on the road, the insurer must fit new original parts, and you pay nothing towards them. Furthermore, where both sides agree to repair rather than settle in cash, the work goes to the agency workshop. Meanwhile our agency repair guide shows how that term works on your own policy.
After the first year, the insurer may use shops that suit the car’s type and year. Parts may be non-original, though of the same grade. Still, the company carries real duties:
- First, it must make sure the work meets proper standards.
- Second, the repair shop must warrant the job.
- Third, you may have the car checked by any approved test centre in the UAE.
- Finally, where the work falls short, the company must take the car back until the shop puts it right.
Disagree with the insurer over the value? Then the Authority names a licensed Surveyor and Loss Adjuster, and the company pays that fee.
Parts, depreciation and the always-new list
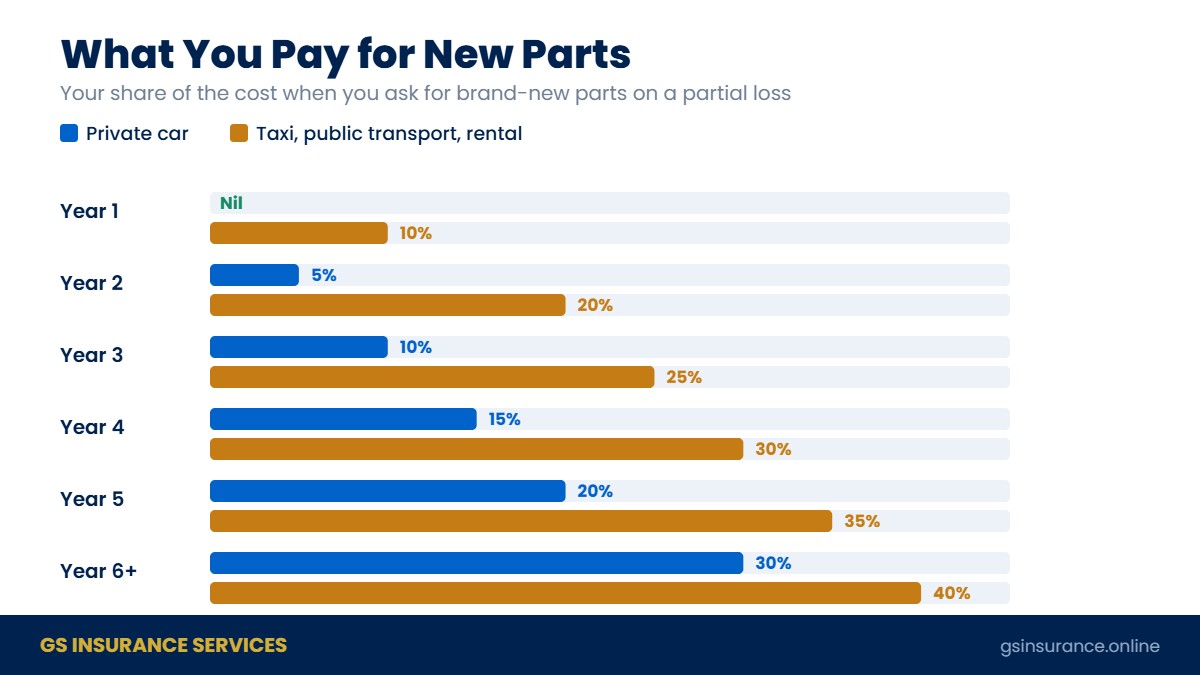
Ask for brand-new parts on a partial loss, and you pay a share of the cost.
| Year of registration and use | Private car | Taxi, public transport, rental |
|---|---|---|
| First | Nil | 10% in the last six months |
| Second | 5% | 20% |
| Third | 10% | 25% |
| Fourth | 15% | 30% |
| Fifth | 20% | 35% |
| Sixth and above | 30% | 40% |
However, one list escapes the deduction entirely. So the insurer must fit new safety parts, and may never use second-hand ones: glass, brake master cylinders, wheel cylinders, calipers, brake cables, hoses and diaphragms, steering boxes, steering racks, steering ball joints and swivels, and seat belts.
When the car is written off
Meanwhile two triggers turn a repair into a write-off.
- Repair costs pass 50% of the market value on the day of the crash.
- Or the chassis or a pillar needs cutting, tightening or welding.
Then the insurer pays market value rather than repairing, still inside the AED 2 million limit. Alternatively it may hand over the same make, model and extras, unless the injured party asks for cash.
Also, the wreck becomes the insurer’s property. Yet the injured party may not be charged for the title transfer or the ownership paper, so long as the car carries no unpaid fines.
When your insurer can claim the money back
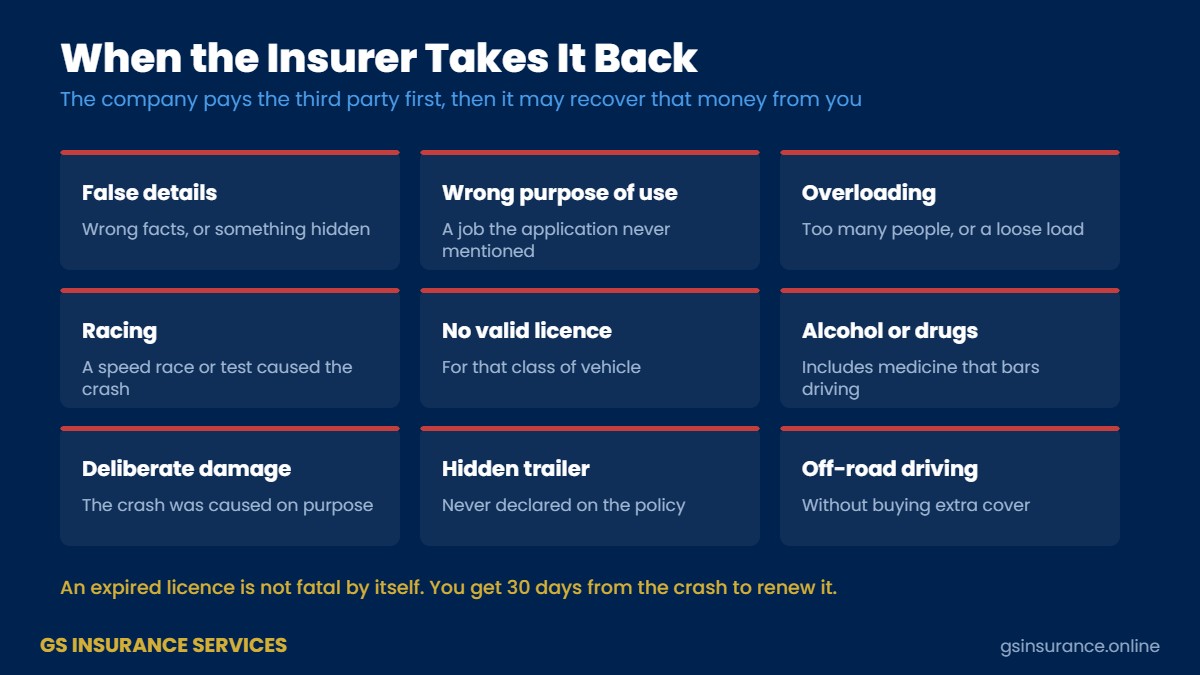
Here is the part drivers underrate. First, the company pays the third party. Then it may take that money back from you. So watch for these cases:
- False details. You gave wrong facts, or hid something that changed the price.
- Wrong purpose of use. Your car did a job the application never mentioned.
- Overloading. Too many people, too much weight, or a load left loose.
- Racing. A speed race or test caused the crash.
- No licence. Nobody in the seat held a valid licence for that class.
- Alcohol or drugs. Also counts medicine that bars you from driving.
- Deliberate damage. Someone caused the crash on purpose.
- Hidden trailer. A trailer caused the crash and you never declared it.
- Off-road use. You left the road without buying extra cover.
Still, one detail helps drivers. An expired licence is not fatal by itself, because the policy gives you 30 days from the crash to renew it.
What third party car insurance excludes
Four exclusions apply. Also, one of them catches drivers out every winter.
- Crashes outside the UAE.
- Natural disasters, including floods, storms, earthquakes and volcanoes.
- War, invasion, riot, nuclear and radioactive events.
- Injury to you, your driver, or staff hurt at work, unless a rider covers them.
That flood point matters here in the UAE. So read our guide to flood coverage before the next rainy season.
Cancelling and getting money back
Neither side may cancel while the vehicle licence stays valid. However, three exceptions exist. Either the licence is cancelled, or a new policy replaces it after the car details change, or the car changes owner.
| Time used | Refund |
|---|---|
| Up to 1 month | 80% |
| Over 1 month to end of month 4 | 70% |
| Over 4 months to end of month 6 | 50% |
| Over 6 months to end of month 8 | 30% |
| Over 8 months | Nil |
Note that a paid or open claim where you caused the crash kills the refund. Meanwhile our cancellation guide walks through the paperwork.
Third party or comprehensive?
Rather than guess, do the sum.
Third party cover suits an older car with a low value, because the full-cover price may creep up towards what the car is worth. Meanwhile full cover suits a financed car, a new car, or any car you could not replace tomorrow.
Remember the ceilings. Full cover costs at most 5% of value for a saloon and 7% for a four-wheel drive, with floors of AED 1,300 and AED 2,000. So weigh that figure against the third party price before you decide.
Arranging your cover
Keep it short. First, check the quote against the legal band for your vehicle class. Second, read the purpose of use on the schedule, because a work vehicle written as private fails at claim time. Finally, ask which licensed insurer issues the policy.
GS Insurance Services arranges third party and full motor cover across all seven emirates. Also, we work as a sales channel for licensed UAE insurance companies, so we tell you which one issues your policy before you pay.
Send your Mulkiya on WhatsApp: +971 52 514 6699 and we will come back with prices. Alternatively, use our contact page or see the car insurance service page.
Running five or more vehicles under one owner? Our dedicated guide to motor fleet insurance in the UAE covers the 30% reduction, the official fleet definition and the cover an insurer cannot legally cut.
Frequently asked questions
Is third party car insurance enough in the UAE?
By law, yes. It meets the rule for registering the car. Still, it pays nothing towards your own car, so weigh it against what your car is worth.
How much does third party car insurance cost?
A four-cylinder private saloon runs from AED 750 to AED 1,300 for the 13-month term. Meanwhile bigger engines and four-wheel drives sit higher.
Does it cover my passengers?
Yes. Passengers count as third parties, except staff hurt at work.
What if the other driver was uninsured?
No insurer stands behind them, so you must chase the driver in person. However, full cover dodges that problem, because your own insurer settles first.
Can I claim a replacement car?
Where someone else hit your private car and you pick repair, yes. The payment runs to AED 300 a day for up to 15 days.
How long do I have to file a claim?
Tell the police and the insurer as soon as you reasonably can. Also, court action must start within three years of the crash, or of the day you learn about the damage.
Does third party cover flood damage?
No. Natural disasters, floods included, sit right outside this policy.
Related guides: car insurance for expats UAE | best car insurance Dubai
Sources
- CBUAE Rulebook – Unified Motor Vehicle Insurance Policy Against Third Party Liability
- CBUAE Rulebook – Motor Vehicle Insurance Tariffs, Decision No. 30 of 2016
- The Official Portal of the UAE Government – Registering vehicles
GS Insurance Services works as a sales intermediary. A licensed UAE insurance company issues and underwrites every policy. This article gives general information based on the published regulation, and it is not advice on a specific policy. Always read your own policy schedule and confirm the terms with your insurer.
