
A car insurance discount in the UAE is not a favour your insurer does you. In fact, most of these cuts sit in the tariff rules, with the exact figure written down. Yet almost nobody asks for them by name.
So here is every cut the rules allow, what each is worth, and the one detail that changes the whole sum. Also, we show the free paper you may demand at renewal, which most drivers never hear about.
The detail that changes every car insurance discount
First, read this before the tables. It decides the money.
Nearly every cut is written as a percentage of the minimum premium, not of the price you were quoted. So the discount is a fixed sum tied to your vehicle class. Also, it does not grow when the quote grows.
Take a four-cylinder private saloon on third party cover. The legal minimum is AED 750. Therefore a 20% claim-free cut is worth AED 150, whether your quote was AED 800 or AED 1,200.
Meanwhile the electric and gas cut is written differently. That one runs on the premium itself, so it behaves the way people expect. Furthermore, our electric car insurance guide covers it in full.

Claim-free years and the loyalty cut
Now the everyday cuts. Both of these apply to individuals.
| Reason | Reduction | Worth on a saloon TPL minimum of AED 750 |
|---|---|---|
| No claim-causing accident last year | 10% | AED 75 |
| None for two years | 15% | AED 113 |
| None for three years | 20% | AED 150 |
| Loyalty, renewing with the same insurer | 10% | AED 75 |
Note the wording on claim-free years. It covers crashes you caused that led to a claim. So a crash where the other driver was at fault should not cost you this cut.
Meanwhile the loyalty cut carries its own condition. It applies when you renew with the same company, and only while the policy stays in your name.

The 50% car insurance discount, and who gets it
Here is the biggest cut in the rules. In short, it is worth half the minimum premium.
Also, six groups qualify, on renewal or on a brand-new policy:
- People working in the medical sector
- Members of the Armed Forces and the Police
- Members of the Civil Defence
- People of determination
- Anyone over 60 years old
- Individuals with an accident-free record
Look closely at the last line. It sits in the same list as the rest, yet it is separate from the 10, 15 and 20 percent ladder above. So an individual with a clean record has a much stronger case than most people think.
Still, the rule says “shall be granted” for this group, while the claim-free ladder says “may”. Therefore name this category directly when you renew.
The free certificate almost nobody asks for
This one is not a cut. Instead, it is the proof that unlocks one.
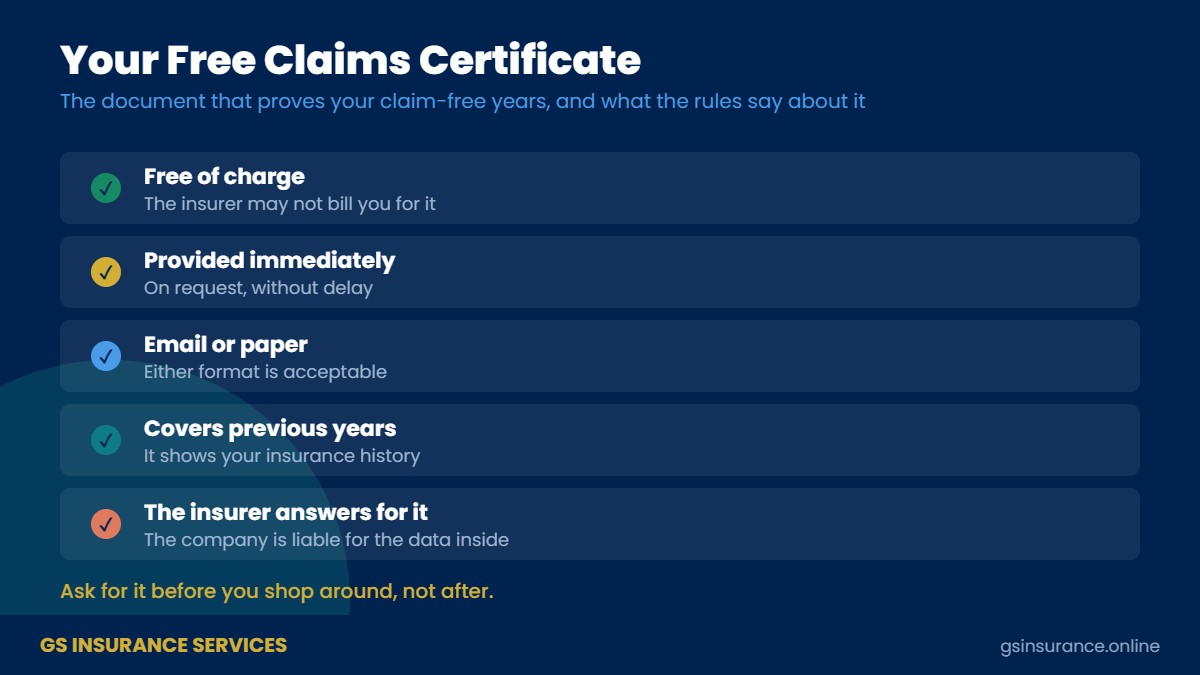
Your insurer must give you, free of charge and at once, a certificate showing your insurance history for the previous years. It may come by email or on paper. Furthermore, the company answers for the data inside it.
That paper is how a new insurer checks your claim-free years. Without it, you are asking them to take your word. So ask for it before you shop around, not after.
Fleet discount for five vehicles or more
Meanwhile businesses have their own cut. In fact, it is the largest one available.
A fleet may get up to 30% of the minimum premium. Then the rules define a fleet plainly: five or more vehicles or motorcycles owned by one natural or legal person.
However, that wording is wider than most owners think. It names ministries, federal and local authorities, government and semi-government bodies, independent bodies, charities, non-governmental groups, companies and individual firms.
So five pickups under one trade licence already counts. Meanwhile our commercial vehicle insurance guide lists the rate bands that the 30% comes off.
The gas and electric car insurance discount
Cars running on gas or electricity may get up to 25% at renewal. However, two conditions shape it.
First, the insurer weighs crashes the car caused that led to claims. Second, this cut lands at renewal, not on a first policy.

Only the highest car insurance discount applies
Now the rule that ties it all together. Where more than one reason exists, only the highest rate applies. In short, they never stack.
So a nurse with three claim-free years does not get 50% plus 20%. Instead she gets 50%, because that is the bigger figure.
| Your situation | Reductions you qualify for | What you actually receive |
|---|---|---|
| Police officer, 2 claim-free years, same insurer | 50%, 15%, 10% | 50% |
| Three claim-free years, same insurer | 20%, 10% | 20% |
| Electric car, one claim-free year | 25%, 10% | 25% |
| Fleet of six vans, two claim-free years | 30%, 15% | 30% |
Therefore your job is simple. Work out which single cut is largest, then ask for that one by name.
Taxis, rental cars and a different rule
Saloon taxis and rental cars sit outside the normal tariff. Instead, the company may agree a rate with the owner, so long as it stays under 6.5% of the vehicle value.
Also, that deal rests on the loss ratio, the technical view and the insurer’s past experience. So a clean claims history matters more here than anywhere else.
Classic and old vehicles
Meanwhile owners of older cars have an option that rarely gets a mention.
For a classic or old car, the third party tariff still applies as normal. Yet the loss and damage price is left to a deal between the owner and the insurer.
Also, the rules define the group. A classic or old car means one at least 30 years old with historic value, artistic industrial value, or a unique design unlike its peers.
Paying by the kilometre
Finally, here is the newest option. It suits drivers who cover few miles.
You may ask the company to price your cover against the kilometres the car really travels. The insurer has the right to do this when you ask, and the price still cannot pass the tariff ceiling.
So where your car mostly sits parked, ask the question. Meanwhile our private car insurance guide lists the top rates that still apply.

What your insurer may never charge
Cuts are worth little if fees claw the money back. Fortunately, the rules close that door.
The insurance company, the agent and the broker may not impose or receive any extra amount without a decision from the Authority allowing it. Also, the company must state the premium clearly on both the policy and the insurance certificate.
So “processing fee”, “issuance charge” and “card fee” have no footing. Simply ask which decision permits the charge. Meanwhile our guide to insurance scams in the UAE covers the rest.
How to claim your car insurance discount
Follow five steps, and you will not leave money behind.
- Ask for your claims-experience certificate first. It is free, and it is your evidence.
- Find your single best cut. Compare 50%, fleet 30%, electric 25%, then the claim-free ladder.
- Name it in writing. Say which category you fall into and attach the proof.
- Check the sum. Remember most cuts come off the minimum premium for your vehicle class.
- Reject unexplained fees. Ask for the decision that permits any extra charge.
GS Insurance Services arranges motor cover across all seven emirates. Also, we work as a sales channel for licensed UAE insurance companies, so we tell you which cuts your case supports before you pay.
Send your Mulkiya on WhatsApp: +971 52 514 6699 and we will come back with prices. Alternatively, use our contact page or see the car insurance service page.
Running five or more vehicles under one owner? Our dedicated guide to motor fleet insurance in the UAE covers the 30% reduction, the official fleet definition and the cover an insurer cannot legally cut.
Frequently asked questions
Can I combine two car insurance discounts?
No. Where several reasons apply, only the highest single rate counts.
Does a car insurance discount come off my quote or the minimum?
Most come off the minimum premium for your vehicle class. However, the gas and electric cut runs on the premium itself.
How much is the no-claims discount in the UAE?
It runs at 10% after one clear year, 15% after two, and 20% after three. Also, each figure comes off the minimum premium for your vehicle class.
Do I lose it if someone else hit me?
The rule covers crashes your car caused that led to a claim. So a crash caused by another driver should not remove it.
Who qualifies for the 50% reduction?
Medical sector workers, armed forces, police, civil defence, people of determination, anyone over 60, and individuals with an accident-free record.
How many cars make a fleet?
Five or more vehicles or motorcycles under one owner, including companies, government bodies and charities.
Is the claims certificate really free?
Yes. Your insurer must supply it at once and at no charge. Furthermore, it answers for the data inside.
Can my broker charge a service fee?
Not without a decision from the Authority permitting it. Ask which decision applies.
Related guides: car insurance renewal UAE | agency repair car insurance UAE | UAE third party car insurance
Sources
- CBUAE Rulebook – Motor Vehicle Insurance Tariffs, Decision No. 30 of 2016
- CBUAE Rulebook – Unified Motor Vehicle Insurance Policy Against Third Party Liability
- The Official Portal of the UAE Government – Insurance
GS Insurance Services works as a sales intermediary. A licensed UAE insurance company issues and underwrites every policy. This article gives general information based on the published regulation, and it is not advice on a specific policy. Always read your own policy schedule and confirm the terms with your insurer.
