
UAE private car insurance runs on one national rulebook. In fact, the Central Bank fixes the wording, the premium limits and the payouts. So every licensed insurer sells the same core policy. However, most drivers never read it. Therefore they miss money they are owed, and they accept quotes above the legal cap.
Here we set out the official numbers in full. Also, we show the parts your insurer must replace brand new, the daily allowance for a replacement car, and the discounts you can ask for today. For fleets and trucks, read our guide to commercial vehicle insurance instead.
What UAE private car insurance must cover
First, you get a choice of two standard policies. Both come from the same regulation.
- Third Party Liability (TPL). This is the legal minimum. In short, it pays other people. However, it pays nothing towards your own car.
- Loss and Damage plus TPL. Generally, drivers call this comprehensive. It also repairs or replaces your own car.
Both run for 13 months, not 12. So your renewal date moves forward each year. Furthermore, the policy names a purpose of use: private, commercial, rental or driving education. Keep yours on private, because a wrong entry lets the insurer refuse the claim.
You also need cover before you get plates. The UAE Government portal lists it plainly as a registration step: get vehicle insurance from an authorised insurer.
UAE private car insurance rates for saloons and 4x4s
To begin with, Table (1) of the tariff regulation caps third party premiums. These figures cover a full 13-month period.
| Vehicle | Minimum (AED) | Maximum (AED) |
|---|---|---|
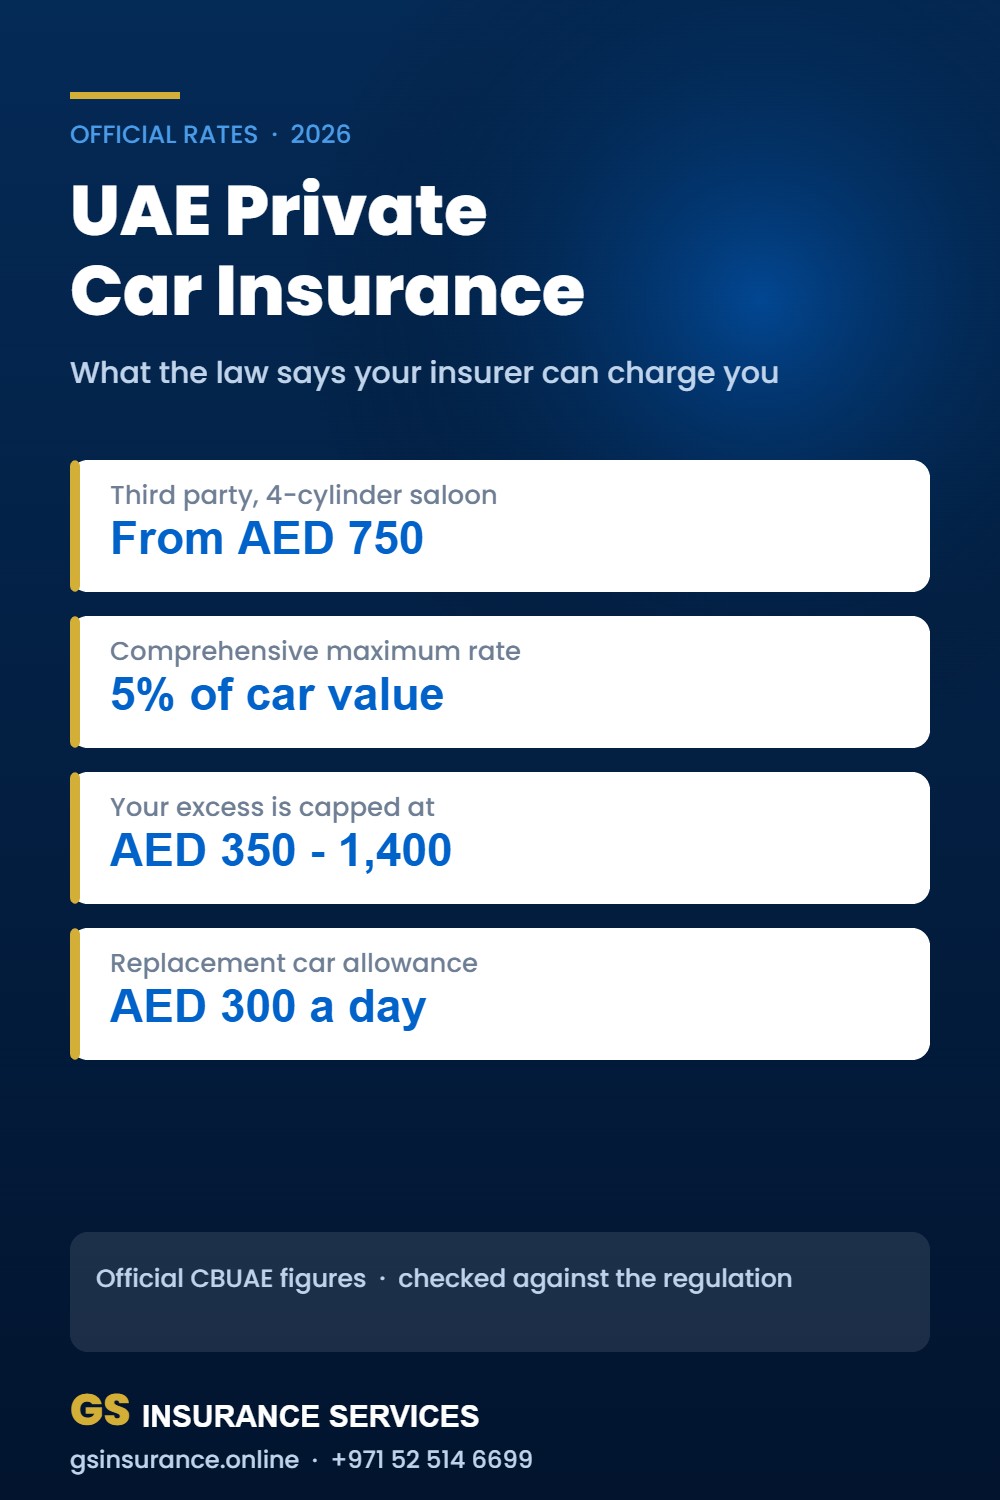
| Saloon, private, 4 cylinders | 750 | 1,300 |
| Saloon, private, 6 cylinders | 850 | 1,400 |
| Saloon, private, 8 cylinders | 950 | 1,600 |
| Saloon, private, over 8 cylinders | 1,300 | 2,100 |
| Four-wheel drive, private, 4 cylinders | 1,000 | 1,750 |
| Four-wheel drive, private, 6 cylinders | 1,050 | 1,900 |
| Four-wheel drive, private, 8 cylinders | 1,100 | 1,950 |
| Four-wheel drive, private, over 8 cylinders | 1,200 | 2,150 |
So a four-cylinder saloon cannot cost more than AED 1,300 for third party cover. If your quote sits higher, then ask the insurer to justify it. Insurers may compete below the ceiling, yet they may not go above it.

Comprehensive UAE private car insurance: floor and ceiling
Meanwhile, Table (2) works differently. It sets a minimum premium in dirhams and a maximum rate as a share of your car’s value.
| Vehicle | Minimum premium (AED) | Maximum rate |
|---|---|---|
| Saloon | 1,300 | 5% of value |
| Four-wheel drive | 2,000 | 7% of value |
Therefore a saloon worth AED 80,000 cannot carry a comprehensive premium above AED 4,000. Meanwhile the floor holds at AED 1,300. Two small extras also sit in the tariff: driver cover at AED 120 and passenger cover at AED 30.
What third party liability actually pays
In fact, this part surprises people. The limits are generous, and they are fixed by regulation.
| What happened | What the insurer pays |
|---|---|
| Injury or death to another person | Whatever the court awards, with no limit |
| Death of your own spouse, parent or child | Up to AED 200,000 per person |
| Damage to other people’s property | Up to AED 2,000,000 per accident |
| Ambulance and transport to hospital | AED 6,770 per injured person |
| Medical treatment | All treatment costs, paid to the hospital |
Now read the second row again, because it matters. Your own spouse, parents and children count as third parties even when you caused the crash. So they stay covered. Meanwhile the insurer may not apply any deductible to a third party’s compensation.

The substitute car allowance most drivers never claim
Notably, here is a right that goes unused every week. If another driver damages your private car, and you choose repair instead of cash, then you can claim a loss of use allowance.
- Up to AED 300 per day.
- Up to 15 days.
- Alternatively, the insurer supplies a similar car in good condition.
The clock starts when you hand over the car, the accident report and the title deed. However, you lose the allowance if you take a cash settlement. So think before you accept cash.

Parts UAE private car insurance must replace brand new
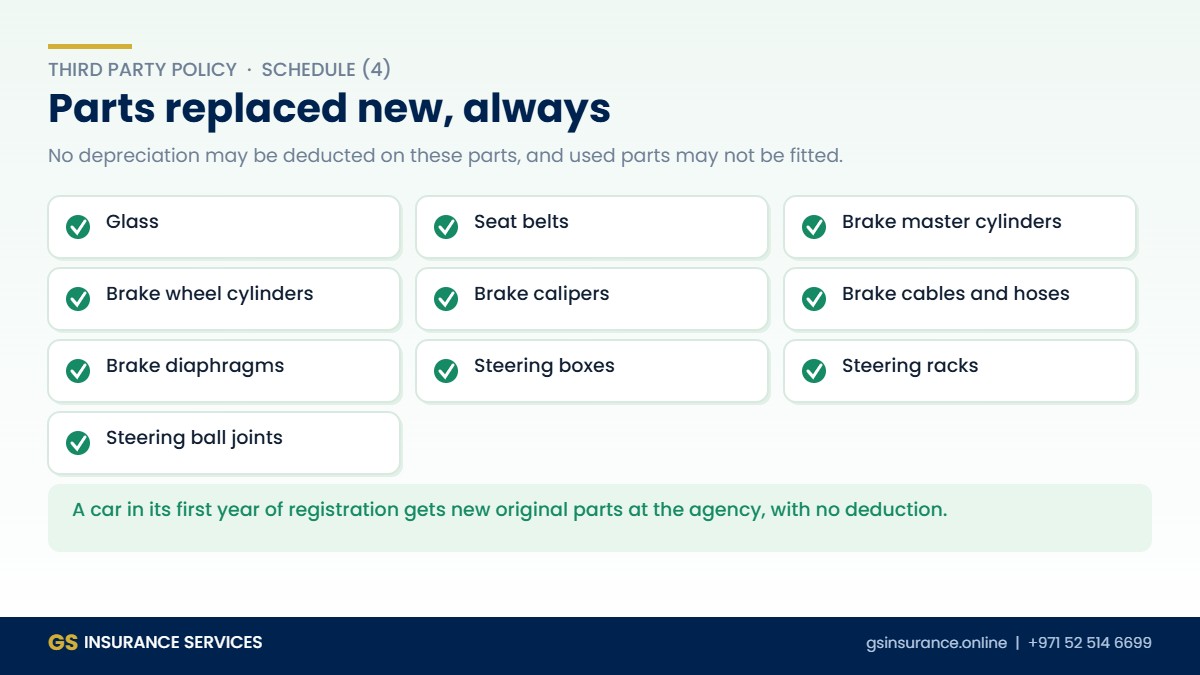
Notably, Schedule (4) of the third party policy names parts that must be replaced with new ones. No depreciation applies to them, ever. In short, safety comes first.
- Glass
- Brake master cylinders, wheel cylinders and calipers
- Brake cables, hoses and diaphragms
- Steering boxes and steering racks
- Steering ball joints and swivels
- Seat belts
Also, a car in its first year of registration gets new original parts at the agency, with no depreciation at all. After that first year, the rules change.
Depreciation on everything else
When you ask for new parts on an older car, you pay a share. Schedule (1) sets it for private cars.
| Year of registration and use | Your share |
|---|---|
| First | Nil |
| Second | 5% |
| Third | 10% |
| Fourth | 15% |
| Fifth | 20% |
| Sixth and above | 30% |
One more rule matters a great deal. If the chassis or a pillar needs cutting or welding after a crash, then the car counts as a total loss. The insurer pays market value instead of repairing it. Likewise, damage above 50% of market value triggers a total loss settlement.
UAE private car insurance excess by car value
Similarly, your excess, or Basic Deductible, follows the car’s value. Schedule (3) caps it.
| Car value | Maximum excess per accident |
|---|---|
| Up to AED 50,000 | AED 350 |
| AED 50,001 to 100,000 | AED 700 |
| AED 100,001 to 250,000 | AED 1,000 |
| Above AED 250,000 | AED 1,200 |
| Above AED 500,000 | AED 1,400 |
On top of that, the insurer may add a percentage. A driver under 25 adds up to 10%. A sports or modified car adds up to 15%. A car modified outside the factory adds up to 20%.

Still, two protections apply. Only the highest percentage counts when several could apply. Also, none of them apply in a total loss. Furthermore, the insurer charges the excess to the driver who caused the accident. So a not-at-fault driver should pay nothing. We explain the whole system in our guide to car insurance excess in the UAE.
UAE private car insurance discounts you can claim
Certainly, the regulation lists these openly. However, insurers rarely offer them first.
- 10% off the minimum premium after one claim-free year.
- 15% after two claim-free years.
- 20% after three claim-free years.
- 10% loyalty discount for renewing with the same insurer.
- 25% at renewal for a car running on gas or electricity.
- 50% for medical staff, armed forces, police, civil defence, people of determination, and anyone above 60.
They do not stack, so only the highest one applies. Also, your insurer must give you a free claims-experience certificate when you ask. Therefore always collect it before you switch. Driving an electric car? Then read our electric car insurance guide.
Nine things that let the insurer come after you
In practice, recourse means the insurer pays the victim first, then recovers the money from you. These cases come straight from the policy.
- You hid or misstated something important when you bought the policy.
- The car did a job other than the purpose written on the policy.
- More passengers rode than the licence allows, or the car carried too much weight.
- A race or a speed test on a public road caused the crash.
- The driver broke the law in a way that counts as a wilful crime.
- Nobody at the wheel held a valid licence for that class of car.
- Alcohol, narcotics or restricted medication affected the driver.
- Someone caused the accident on purpose.
- A trailer joined the car without the insurer’s agreement.
One kind detail sits in the same policy. If your licence expired, then you keep cover as long as you renew it within 30 days of the accident. Meanwhile off-road driving stays excluded unless you buy a rider first.
Cancelling UAE private car insurance and getting money back
Meanwhile, a third party policy cannot simply be cancelled while the car licence stays valid. Instead, it ends when you cancel the registration, change the car details, or transfer ownership. Then the insurer refunds part of the premium.
| How long the policy ran | Refund |
|---|---|
| Up to 1 month | 80% |
| 1 to 4 months | 70% |
| 4 to 6 months | 50% |
| 6 to 8 months | 30% |
| Over 8 months | Nil |
Still, these bands apply only to the third party policy. Comprehensive policies follow their own schedule, which we cover in our guide on how to cancel car insurance in the UAE.
How to buy UAE private car insurance
Meanwhile the buying process stays simple. First, note your car’s cylinders, value and registration year. Second, decide between third party and comprehensive. Third, check the quote against the caps above. Finally, ask for every discount you qualify for.
Also, GS Insurance Services arranges private car cover across all seven emirates, for saloons, station wagons and 4x4s. We compare rates from licensed UAE insurers, so you see the real market before you commit.
Get your quote on WhatsApp: +971 52 514 6699 and send us your Mulkiya. Alternatively, use our contact page, browse the car insurance service page, or read our full Dubai car insurance guide.
Frequently asked questions
How much is UAE private car insurance?
Firstly, third party starts at AED 750 for a four-cylinder saloon. Comprehensive starts at AED 1,300 for a saloon and AED 2,000 for a 4×4.
Is third party UAE private car insurance enough?
Generally, it meets the law and it pays other people well. However, it pays nothing for your own car. So choose comprehensive if you cannot afford to repair your car yourself.
Does my family get covered if I cause the accident?
Yes, because your spouse, parents and children count as third parties. In case of death, the limit is AED 200,000 per person.
Can I get a free replacement car?
Yes, so long as another driver damages your car and you choose repair. The allowance runs up to AED 300 a day for up to 15 days.
Which parts get replaced new without depreciation?
In short, glass, brakes, steering parts and seat belts. Schedule (4) of the policy lists them, and no depreciation applies.
What happens if my licence expired?
Fortunately, you keep cover if you renew the licence within 30 days of the accident date.
Why is my policy 13 months?
Because the regulation fixes the insurance period at 13 months for every motor policy in the UAE.
Related guides: agency repair cover | flood coverage UAE car insurance | car insurance discounts UAE
Sources
- CBUAE Rulebook – Unified Motor Vehicle Insurance Policy Against Third Party Liability
- CBUAE Rulebook – Motor Vehicle Insurance Tariffs, Decision No. 30 of 2016
- The Official Portal of the UAE Government – Registering vehicles
GS Insurance Services works as a sales intermediary. A licensed UAE insurance company issues and underwrites every policy. This article gives general information based on the published regulation, and it is not advice on any specific policy. Always read your own policy schedule and confirm the terms with your insurer.